CLIENT NOTICES | Please visit www.spli.com/clientnotices for updated information regarding FLORIDA E-VERIFY REQUIREMENTS, ERC CLAIMS, and NO TAX ON TIPS OR OT.
August 11, 2026

USL&H is a federal act, whereas workers’ compensation is governed by state laws, with each state acting independently regarding coverage. Not everyone can issue a USL&H certificate, but SPLI can offer federal certificates for most states.
What Is USL&H Coverage?
USL&H coverage refers to workers’ compensation mandated under the federal Longshore and Harbor Workers’ Compensation Act (LHWCA). The law establishes a federal workers’ compensation system for certain employees engaged in maritime work.
The LHWCA applies when employees perform maritime duties on navigable waters or in adjoining areas like piers, docks, and marine railways. It offers medical care, disability, rehabilitation, and survivor benefits for covered work-related injuries or illnesses.
Working near water does not automatically place an employee under USL&H coverage. The work performed and the location where it occurs must be considered together.
Who Qualifies for USL&H Coverage?
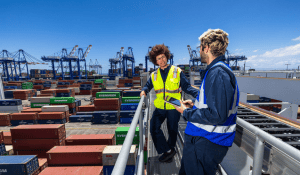
USL&H coverage generally applies to employees working in qualifying maritime occupations, including:
- Shipbuilders
- Longshore workers
- Repair and maintenance crews
- Harbor construction workers
- Shipbreakers
USL&H coverage is not based on a company’s industry or an employee’s job title alone. Two employees working for the same marine business may fall under different systems because their responsibilities and work locations differ. The determination generally centers on three questions:
 1. What Work Does the Employee Perform?
The employee must generally perform qualifying maritime work. This may include:
- loading or unloading vessels
- repairing ships
- building vessels
- dismantling vessels
- performing certain harbor construction activities
Employers should document the work an employee performs instead of relying on a broad title such as laborer, maintenance employee, or supervisor.
2. Where Is the Work Performed?
Qualifying work may take place on navigable waters or in an adjoining maritime area used for covered vessel-related activities. A facility’s proximity to water is not enough by itself. How the location is used and what the employee does there also matter.
3. Is the Employee a Vessel Crew Member?
Not every employee working for a marine business qualifies for USL&H coverage under the LHWCA. The LHWCA excludes masters and members of a vessel’s crew.
It also identifies other categories that may be excluded when state workers’ compensation applies, including certain employees working exclusively in clerical, secretarial, security, or data-processing roles.
For example, an administrative employee working exclusively in an office at a marine terminal may be treated differently from an employee repairing vessels at the same facility.
Because exclusions depend on the employee’s responsibilities and other account-specific facts, employers should not make a coverage determination based only on the company’s location or industry.
USL&H vs. The Jones Act
The Jones Act was established to protect seamen — the captain and crew members of ships — when they’re injured on the job. It provides workers’ compensation coverage for workers on ships, from cargo ships and barges to oil rigs.
Like employees who qualify for USL&H coverage, seamen may fall outside the traditional state workers’ comp system, making the Act essential for their protection.
USL&H coverage generally provides no-fault workers’ compensation benefits, meaning an eligible employee does not ordinarily need to prove employer negligence to receive benefits. The Jones Act, by comparison, allows eligible seamen to pursue claims based on employer negligence.
What If You Aren’t Covered by Either?
If you don’t qualify for federal USL&H coverage, you may be eligible for workers’ comp under your state’s specific laws. Which one will depend on the type of work you do and where. For example:
- Land-based employees working away from navigable waters are often covered under their state’s workers’ comp laws.
- Federal employees may qualify for a different set of government coverage unrelated to the marine industry under an extension of the USL&H Law.
In other cases, you may qualify for state-regulated workers’ compensation.
How Does USL&H Differ From Workers’ Compensation?
Workers’ compensation is a state-regulated form of coverage that provides benefits for qualifying work-related injuries or illnesses. Workers’ comp generally operates as a no-fault system, meaning employees typically don’t need to prove employer negligence to receive benefits.
However, coverage is still subject to state-specific requirements and exclusions. Benefits may include medical care and a portion of lost wages.
 While both USL&H coverage and state workers’ comp provide protection for qualifying work-related injuries, they operate under different legal frameworks.
Depending on an employee’s duties and where the work is performed, a business may need state workers’ comp coverage, USL&H coverage, or both across its workforce.
Employers subject to the LHWCA must secure Longshore coverage through an authorized insurance carrier or receive authorization from the Department of Labor to self-insure.
The LHWCA establishes federal requirements for qualifying maritime employees, while state workers’ compensation requirements vary by state. Those differences can affect how coverage is arranged, reported, and documented, making an employee’s actual duties and work location important when determining which system applies.
USL&H Coverage vs. the Jones Act vs. State Workers’ Compensation
USL&H coverage, the Jones Act, and state workers’ compensation can all address work-related injuries, but they apply to different employees and use different claim processes.
|
USL&H Coverage |
Jones Act |
State Workers Comp |
|
|
Governing authority |
Federal Longshore and Harbor Workers’ Compensation Act (LHWCA), administered by the Department of Labor (DOL) |
Federal maritime law under 46 U.S.C. § 30104. |
State workers’ comp law. Rules and requirements vary by state. |
|
Typical covered employees |
Certain longshore workers, harbor workers, shipbuilders, ship repairers, shipbreakers, and other qualifying maritime employees |
Seamen, including captains and crew members, with a qualifying connection to a vessel in navigation. |
Most land-based employees, under the rules of the applicable state. |
|
Typical location of labor |
Navigable waters and adjoining maritime areas including piers, docks, wharves, terminals, shipyards, dry docks, and harbor construction sites. |
On or in service of a vessel, such as a ship, tug, barge, or crew boat. |
Land-based sites, such as offices, shops, warehouses, construction sites, and manufacturing facilities |
|
Claims administration |
Federal Longshore claims process, generally involving employer, provider, or claims admin. |
Handled through a civil action, generally alleging employer negligence. |
Handled through the state workers’ comp system |
This comparison is a starting point, not a final coverage determination. In practice, small details like an employee’s regular duties, exact worksite, connection to a vessel, and the nature of the task can shift which coverage actually applies.
How to Get State-Regulated Workers Comp
Workers’ comp questions are always easier to sort out before an injury occurs, especially as a business grows or an employee’s role shifts.
Start by gathering detailed information about your business operations and employees, including where each employee works, the duties they perform, and whether any part of the job could fall under federal maritime law.
From there, an experienced provider can help evaluate the applicable requirements and establish the appropriate coverage.
Through its PEO program, SPLI helps eligible employers coordinate workers’ comp coverage with payroll, claims support, and compliance resources. That coordination can make it easier to keep payroll records, job classifications, and coverage needs aligned as roles and worksites change.
|
WANT A BROADER LOOK AT WORKERS' COMPENSATION COVERAGE? For more on how the right coverage supports employers with mixed and evolving workforces, explore our workers’ compensation resources. |
LEGAL DISCLAIMER:
The information provided on this website does not, and is not intended to, constitute legal advice; instead, all information, content, and materials available on this site are for general informational purposes only. Information on this website may not constitute the most up-to-date legal or other information. This website contains links to other third-party websites. Such links are only for the convenience of the reader, user, or browser; we do not recommend or endorse the contents of the third-party sites.
Readers of this website should contact their attorney to obtain advice with respect to any particular legal matter. No reader, user, or browser of this site should act or refrain from acting on the basis of information on this site without first seeking legal advice from counsel in the relevant jurisdiction. Only your individual attorney can provide assurances that the information contained herein – and your interpretation of it – is applicable or appropriate to your particular situation. Use of, and access to, this website or any of the links or resources contained within the site do not create an attorney-client relationship between the reader, user, or browser and website authors, contributors, contributing law firms, or committee members and their respective employer